 Skip to content
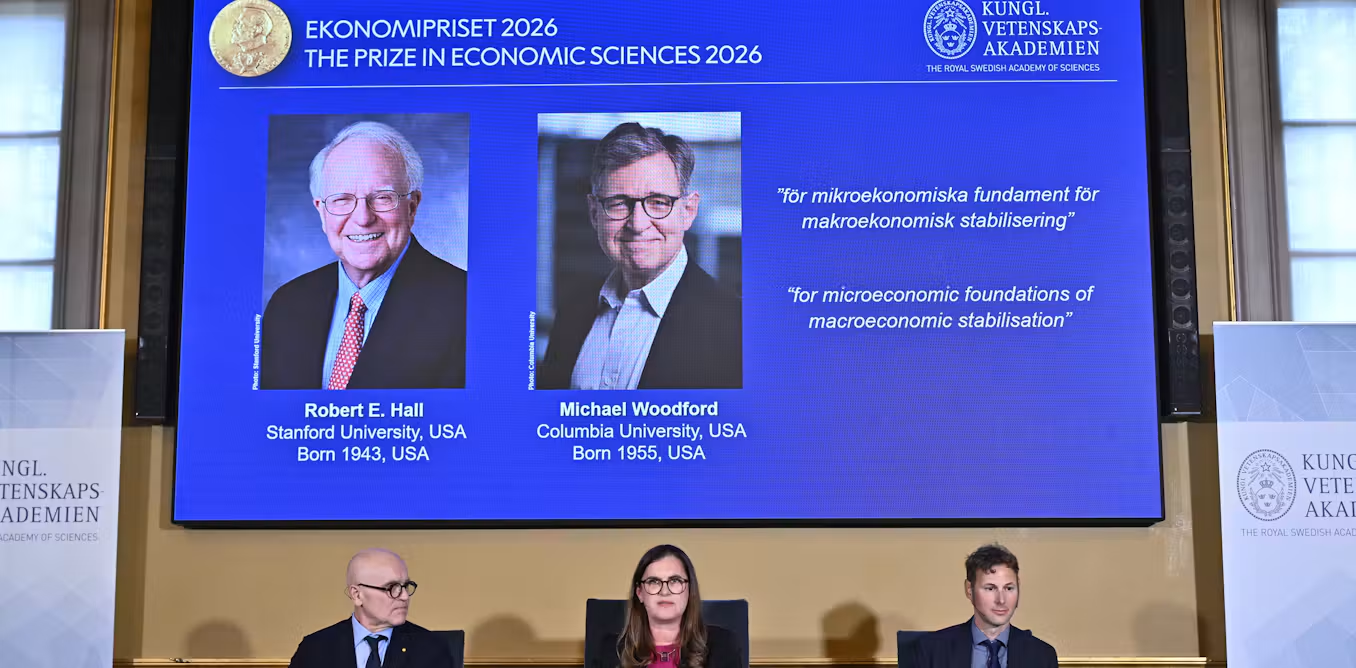
This year, the Royal Swedish Academy of Sciences awarded the American economists Robert E. Hall and Michael Woodford the Nobel Prize for Economic Sciences. The award was given in recognition of her development of macroeconomic models that helped reduce the length and depth of economic downturns.
According to academia, the work of economists in macroeconomic modeling gave policymakers additional tools to balance the economic cycle. As well as reducing the severity of the declines, their work also helped to cool the potential negative effects of economic booms.
The economy is known to follow cycles of recession and boom – and economists have long sought to find ways to tame these. More than a century ago, British economist John Maynard Keynes developed an approach to managing the economy that became known as Keynesianism.
Previously, the classic “laissez-faire” approach dominated. According to this doctrine, in an economic downturn, the markets would eventually clear and the economy would rebound. Any attempt by the government to directly influence the economy would not work and might even make things worse.
Keynes disagreed with the classical view. He believed that the economy could be locked in a downward spiral that would deepen recessions and lead to economic depression. Instead, he argued that governments can actively use the levers of monetary policy (adjusting interest rates) and fiscal policy (lowering taxes and government spending) to improve the health of the economy.
In the aftermath of the 1929 Wall Street Crash, the United States was in a deep economic depression. Franklin D. Roosevelt won a landslide presidential victory in 1932 and his “New Deal” approach to economic policy was similar to that advocated by Keynes. The US economy recovered, and the Keynesian school would dominate politics in many advanced economies after World War II.
But the oil crisis of the 1970s changed everything. The Keynesian approach was ineffective in dealing with low growth, spiraling inflation and high unemployment. Ronald Reagan and Margaret Thatcher won elections in the United States and Great Britain with promises of “smaller government” economic policies, including lower taxes, privatization and deregulation. Keynesianism needs rebuilding.
Decisions of consumers and businesses
Hall and Woodford became part of the “New Keynesian” school that emerged in the 1980s. Their approach was to build models that looked at the decisions of millions of individuals and businesses rather than just taking into account macroeconomic variables such as production, inflation, consumption and unemployment.
Hall, from Stanford University in California, is an expert in consumer theory. According to his “random walk hypothesis,” households’ decisions about whether to spend or save were directly influenced by their expectations about future income and economic conditions. In other words, they weren’t just based on their current financial conditions. Since consumption accounts for about 70% of GDP in advanced economies, these insights were important.
© Johan Jarnestad/The Royal Swedish Academy of Sciences, CC BY-NC-ND
Woodford, of Columbia University in New York, is an expert in supply-side macroeconomics, specifically the role that expectations play in price setting and inflation. In his 2003 book, Interest and Prices: Fundamentals of a Theory of Monetary Policy, he demonstrated that a central bank can influence economic activity by changing the public’s expectations about what may happen with interest rates in the future.
Until the 1990s, central bank policy was secretive and could sometimes surprise the markets. Hall and Woodford’s insights changed this. In the aftermath of the 2008 global financial crisis, the central banks of most major advanced economies adopted an approach known as “forward guidance”.
This policy has provided central bank governors with more transparency about their monetary policy intentions. Forward Guidance policy announcements provide a clear assessment of both the economic outlook and how this may affect inflation. They also determined how central bank policy might respond to these assessments.
As with most policy approaches, forward leadership has both advocates and critics. Research by the European Central Bank shows that clear communication from central banks reduces short-term interest rate volatility. There is also some evidence that after the 2008 financial crisis, expectations that inflation would remain low helped keep interest rates down. This likely encouraged spending and investment, which aided economic recovery.
But critics believe the forward guidance will have no impact on long-term interest rates and say it is debatable whether it will have an impact on short-term rates. They also argue that expectations about interest rates can undermine the credibility of central banks. This could happen if economic policy needs to be changed, for example to deal with sudden shocks.
The conflicts in the Middle East and Ukraine are driving up energy prices and inflation expectations. The forward guidance of many central bankers points to higher inflation and perhaps the need for higher interest rates.
Anyone coming from a fixed interest rate environment might be skeptical of the idea that policy tools can lower short-term interest rate expectations. This is not to say that Hall and Woodford’s work was not transformative. But economies are tricky beasts – and debates around central bank policy are sure to continue.
